
by Martin Armstrong, Armstrong Economics:
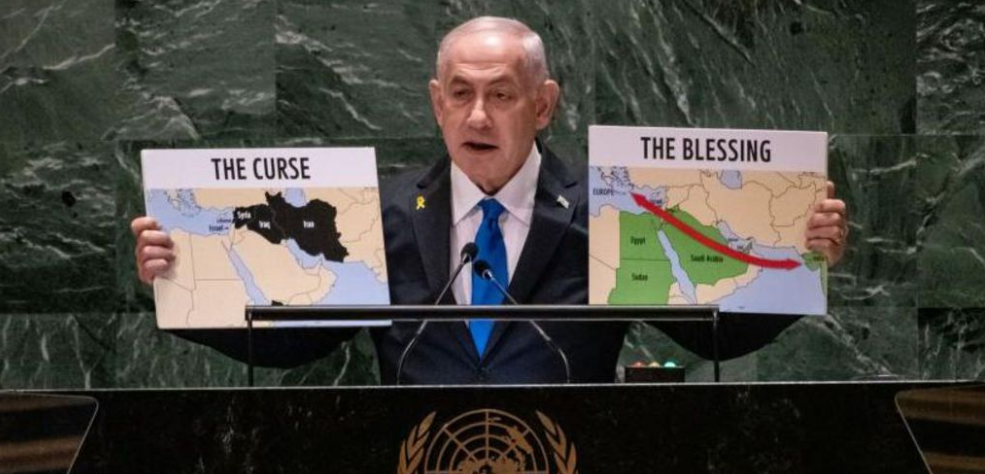
I have reported that Trump was mislead into this unwinnable war with Iran, which has been planning for it since 1979. They had amassed the largest stockpile of balistic missiles and understood the way to fight Israel was to overwhelm their dome defense. Israeli Prime Minister Benjamin Netanyahu is going to run for reelection in October. However, I would not put it past him to pull a Zelensky to retain power. He has implied that he may be considering taking unilateral action to prolong a costly and unwinnable war with Iran, even as Washington and Tehran appear to be close to an interim deal to open the Strait of Hormuz. Trump keeps trying to exit and Netanyahu tries to keep the US in to fund his war.
TRUTH LIVES on at https://sgtreport.tv/
Iran’s investment in ballistic missiles was a deliberate strategic choice, made in the context of its long-standing tensions with the U.S. and Israel. This decision was driven by the understanding that the way to defeat Israel was to overwhelm its defense and that would take a vast supply to compel Israel to eventually run out of missiles.
There is no evidence that Netanyahu has EVER pursued a peace agreement with Iran. Instead, his decades-long career has been defined by consistent, vocal, and active opposition to diplomatic engagement with Tehran, favoring military and economic pressure to prevent Iran from acquiring nuclear weapons. I have stated many times that the primary directive of a Neocon is to reject any communication with a deemed enemy. There is NEVER a desire of peace. With both sides at each other’s throats, there is no solution militarily. Netanyahu is a threat to Israel the same as Zelensky is a threat to Ukraine. Neither consider the civilians who are killed in the process.
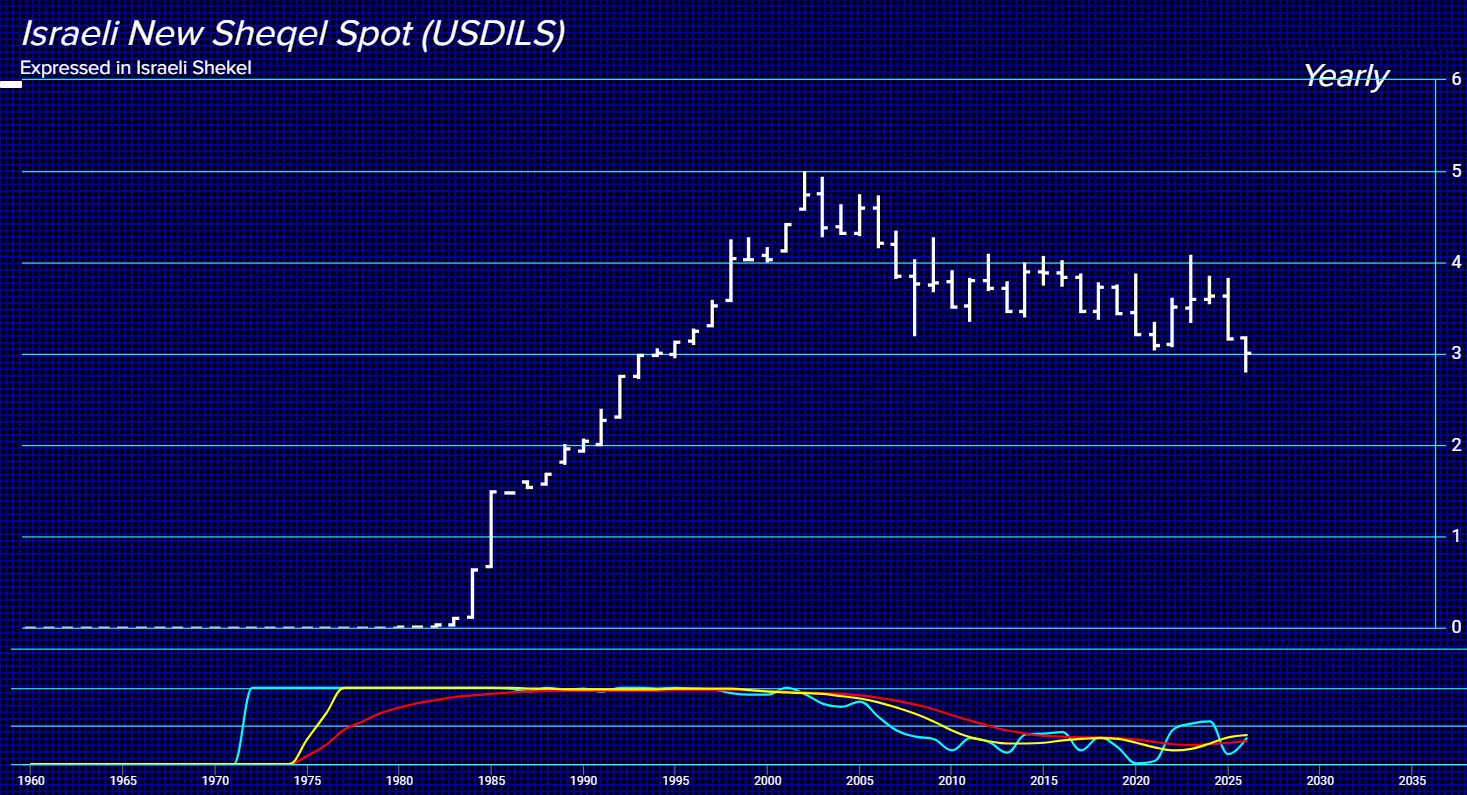
Nonetheless, the shekel reached its weakest point in modern history in May 2002, when the exchange rate hit 4.916 ILS per 1 USD. Since that peak, the currency has generally strengthened. By 2025, the average annual exchange rate was around 3.77 ILS/USD, and in 2026 it has traded significantly lower (stronger shekel), around 2.80-3.00 ILS/USD. This has been driven in part due to the High-Tech and Foreign Investment factors (Capital Flow). Israel has a powerful high-tech sector that attracts massive foreign investment. A significant portion of this investment comes from the US, creating constant demand for shekels.
Then there is the “Nasdaq Effect” and Institutional Hedging. Israeli pension funds and institutional investors hold vast portfolios of US stocks, particularly in technology. To manage currency risk, they engage in “hedging” thereby selling dollars and buying shekels. When US markets, especially the tech-heavy Nasdaq, rise, the value of these portfolios increases, prompting them to buy even more shekels to rebalance their currency exposure. This creates strong, self-reinforcing demand for the local currency.
The Bank of Israel has maintained relatively high interest rates to control inflation. It has been these higher interest rates that have made shekel-denominated assets more attractive to investors, increasing demand for the currency.
Read More @ ArmstrongEconomics.com


