
by Kerry Lutz, Financial Survival Network:
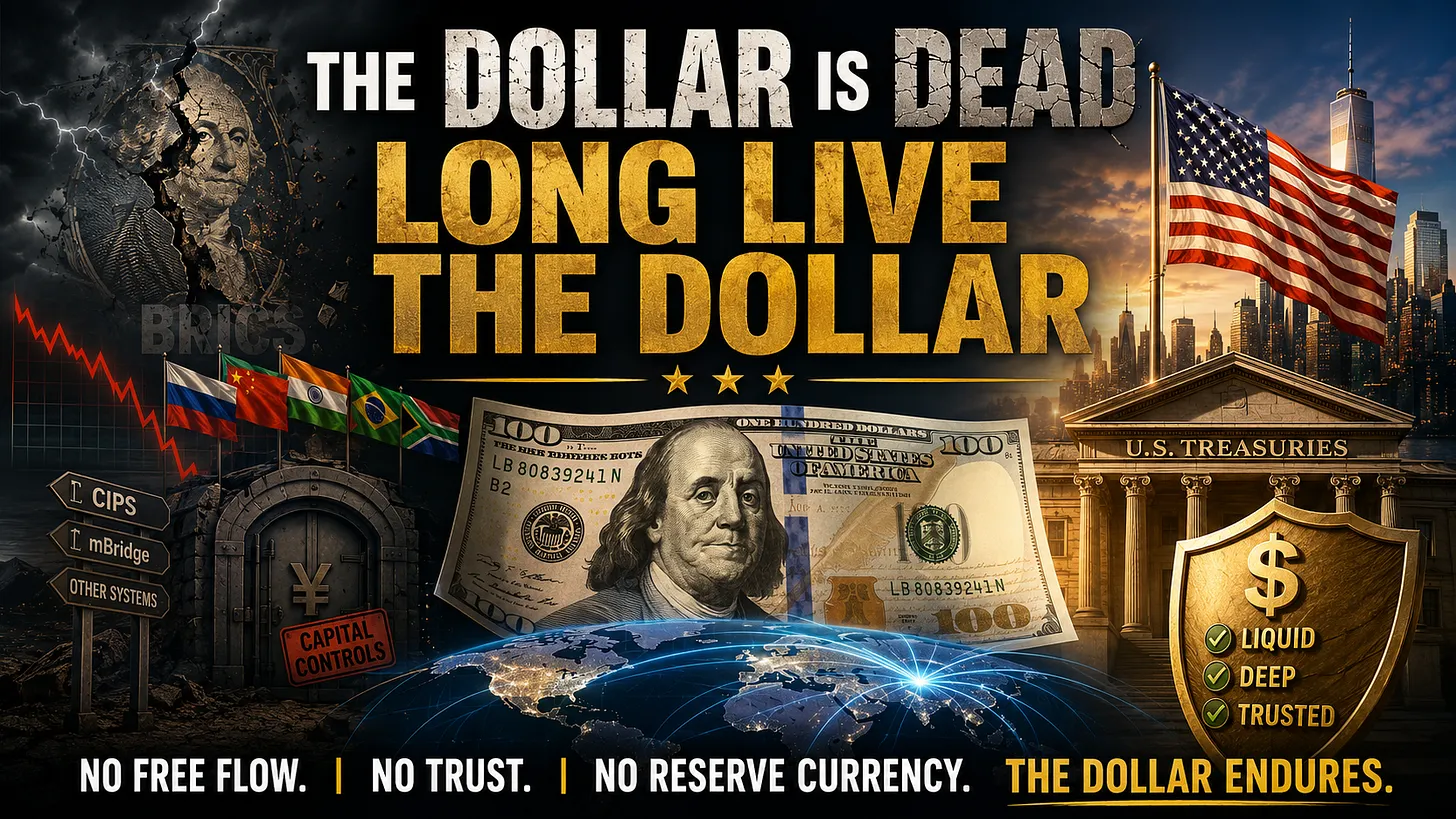 Why the “De-Dollarization” Narrative Keeps Misunderstanding International Capital Flows
Every few years, the macro financial media enters a collective frenzy over the same recurring headline: De-dollarization has arrived.
The catalysts always look convincing on paper. Central banks buy gold at a multi-decade pace. BRICS summits issue grand communiqués. China’s Cross-Border Interbank Payment System (CIPS) processes tens of trillions in volume, and mBridge settles non-dollar trade in seconds.
Yet during this exact period, the Renminbi’s share of global payments sat below 3%. The dollar still anchors nearly 50% of global SWIFT traffic and roughly 60% of central bank reserves.
TRUTH LIVES on at https://sgtreport.tv/
This gap between headline panic and financial reality points to a fundamental truth about international market structure: The old, unassailable post-WWII dollar consensus is dead, but the dollar’s operational supremacy endures—because there is simply nowhere else for global capital to go.
1. Capital Flows and the “Outside-In” View
As our good friend economic forecaster Martin Armstrong has spent decades pointing out via his Economic Confidence Model, financial markets do not move linearly, and currencies are not valued in a vacuum. Armstrong’s core contribution to capital flow analysis is his “outside-in” principle: capital moves globally like a herd of wild animals, fleeing sovereign risk and seeking deep, liquid safe havens.
Armstrong famously describes the major global reserve currencies as the “three ugly sisters”—the U.S. Dollar, the Euro, and the Japanese Yen. The dollar doesn’t win because it is pristine; it wins because it is the least structurally broken sister. “It’s not about gold, and it’s not about moral purity—capital flows to where it can hide, trade, and exit without state confiscation. The dollar is the best-looking ugly sister.”
Or as we like to say, “The US Dollar is the best looking house in Baltimore.”
When you examine international market structure through Armstrong’s lens, the “de-dollarization” narrative crumbles. Financial systems aren’t judged by the length of their payment pipes; they are judged by where capital flees when panic strikes.
2. The $10 Billion Weekend Test
To understand why China cannot dethrone the dollar, stop reading geopolitical communiqués and run a simple institutional mental model.
Imagine you are the Chief Risk Officer of a major European hedge fund. It’s 4:00 PM on a Friday. You have $10 billion in cash that you must park safely over the weekend. You have three choices:
1. Park it with the State Bank of China. You get a decent yield, but China maintains strict capital controls. If a geopolitical crisis erupts over the weekend, Beijing can—and will—freeze your capital account. You cannot move that money out without state permission.
2. Park it with Deutsche Bank. You are exposed to a fragmented European bond market, perpetual structural bail-in risk, and a eurozone banking sector that Armstrong has long warned is systematically crippled by holding unbacked sovereign debt from high-deficit member states.
3. Park it with Jamie Dimon at JPMorgan (or in U.S. Treasuries). You get deep, liquid, legally enforceable property rights. You can move $10 billion at 8:00 AM on Monday morning without asking a politburo for approval.
Where do you park the money?
You call Jamie. Every single time.
That single operational reality destroys the theoretical case for the yuan as a global reserve currency.
3. The Capital Control Paradox
Beijing understands this limitation better than Western commentators do. A currency becomes a global reserve currency only when foreign institutions can:
Acquire it freely
Hold it safely
Move it without permission
Trust an independent court to enforce property rights
Beijing permits none of these things.
China keeps strict capital controls in place to hold the domestic savings of 1.4 billion people hostage inside its banking system. This captive pool of capital is the only mechanism keeping China’s heavily indebted property developers, local government financing vehicles, and state-owned enterprises solvent.
Read More @ khlfsn.substack.com
